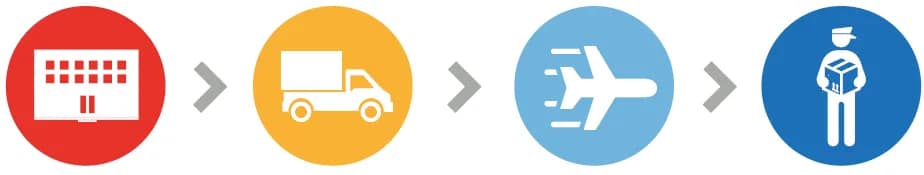
DDP (Delivered Duty Paid) means the seller delivers goods to the named destination cleared for import and takes responsibility for the import formalities and applicable duties. It can help avoid an unexpected border payment for the customer, but the commercial and tax arrangements must be set up correctly before the goods move.
What does DDP mean in practice?
DDP is an agreed delivery term, not a substitute for planning the import. It assigns the seller the task of clearing the goods for import, completing the required customs formalities and paying applicable duties to bring them to the named destination. The parties should record the named place, the party making the import declaration and how the relevant costs are accounted for.
A DDP label alone does not settle a retailer’s wider tax obligations. Import VAT, customs valuation and the documentation required for a shipment depend on the goods and the transaction. Obtain qualified advice before moving stock or making a customer-facing claim about charges.
How does DAP differ from DDP?
DAP means Delivered at Place. Under that term, the seller delivers goods at the named place ready for unloading, while the buyer normally handles import clearance and applicable import charges. The practical difference is important: DDP puts the seller in charge of import clearance and duties, while DAP normally leaves those import responsibilities with the buyer.
Who is the importer of record, and why does it matter?
The importer of record is the party identified for the import process. The role, declarations and supporting documents need to be agreed before stock travels, because uncertainty can delay clearance and warehouse receipt.
Pro FS does not act as importer of record for clients. Goods must be import-cleared and Movement Reference Numbers (MRNs) provided before Pro FS can accept client goods into its warehouse. Pro FS is a delivery address only for customs documentation purposes.
What VAT and duty apply when goods enter the UK?
Import duty and import VAT can depend on the product, its origin, value and the customs declaration. The right treatment must be established for the particular goods and transaction; it should not be inferred from a general article or another retailer’s shipment.
Pro FS is not a tax adviser or VAT expert. Businesses importing and retailing in the UK should seek advice from a qualified tax adviser if they need help with UK VAT registration or compliance. When comparing customs, transport and fulfilment proposals, ask who accounts for import duty and VAT and how VAT is shown. Do not assume a supplier’s price includes VAT.
What changes when selling from the UK to the EU?
An order despatched from the UK to an EU customer can create EU import and VAT considerations. The EU Import One Stop Shop (IOSS) is an optional VAT scheme for qualifying distance sales of goods imported from outside the EU in consignments with an intrinsic value of no more than €150; it does not cover excise goods. It is not automatic, and it does not apply simply because an order falls below that value.
Pro FS is not a tax adviser. Retailers wishing to sell into the EU must take their own tax advice to ensure compliance with IOSS registration and EU VAT laws. This is particularly important when deciding where stock is held, who is responsible for the import and what is shown to the customer at checkout.
Why does holding UK stock change delivery for an overseas brand?
For an overseas brand, importing stock into a UK warehouse moves the inbound customs step to the stock shipment rather than each individual customer parcel. Once import-cleared goods have been accepted into the warehouse, orders for UK customers can be despatched from UK stock. This can make the customer journey simpler, but it does not transfer the brand’s import, VAT or customs-compliance responsibilities to Pro FS.
What should be agreed before stock arrives?
- The named importer of record and the party responsible for the customs declaration.
- Accurate product descriptions, origin, value and any other information required for clearance.
- The delivery term, named destination and how duty, import VAT and carrier charges are handled.
- The MRN and clearance documents Pro FS needs before accepting goods into the warehouse.
- The VAT treatment shown in each supplier or carrier proposal.
- Advice from a qualified customs or tax professional where the transaction requires it.
Frequently asked questions
Does Pro FS act as importer of record?
No. Pro FS does not act as importer of record for clients. Goods must be import-cleared and MRN numbers supplied before Pro FS can accept them into the warehouse, and Pro FS is a delivery address only for customs documentation purposes.
Can Pro FS help with VAT registration or IOSS?
Pro FS is not a tax or VAT adviser. A retailer should obtain advice from a qualified tax adviser on UK VAT registration, IOSS registration and EU VAT compliance before making its own arrangements.
Does DDP cost more than DAP?
DDP does not remove import charges; it allocates responsibility for import clearance and applicable duties to the seller. The seller’s price may reflect those costs. Compare proposals line by line, including transport, duty, import VAT, carrier or customs charges and the stated VAT treatment.
Can duty or VAT be reclaimed when goods are returned?
A return does not automatically create an entitlement to reclaim duty or VAT. The possible treatment depends on the facts, the declarations and the relevant customs and tax rules. Seek qualified customs or tax advice before relying on a particular returns process.
Will Pro FS accept goods that are not import-cleared?
No. Client goods must be import-cleared and accompanied by MRN numbers before Pro FS can accept them into the warehouse.
Can Pro FS ship EU orders under DDP?
The appropriate delivery arrangement depends on the goods, destination, importer responsibilities and the retailer’s tax position. Pro FS does not act as importer of record; discuss the fulfilment requirement with Pro FS and obtain qualified customs and tax advice before committing to a DDP customer proposition.